Table of Contents
Two rupee accounts, two purposes, two very different tax outcomes — and, from this year, two new remittance forms most NRIs haven’t heard of yet.
182 Days
0%
30%+
$1 Million
Why This Matters Right Now
Every NRI who has ever searched “NRE vs NRO” has landed on an article written for an earlier rulebook. Two changes make 2026 different from every prior year:
- The Income-tax Act, 2025 came into force on 1 April 2026, replacing the 1961 Act. Tax rates and deduction limits are unchanged, but the exemption for NRE interest — long cited as “Section 10(4)(ii)” — now sits in Schedule II of the new Act. Returns for income earned up to 31 March 2026 still use the old section numbers; income from FY 2026-27 onward follows the new Act.
- Form 15CA and Form 15CB have been renamed Form 145 and Form 146, effective for every remittance made on or after 1 April 2026. This is the single most important operational change for anyone repatriating money out of an NRO account — the ₹5 lakh threshold for requiring a Chartered Accountant’s certificate is unchanged, but the form names, and the sections of law behind them, are not what most bank websites still describe. Form 13 (the lower/nil-TDS certificate) is now Form 128.
Everything below reflects the position as it stands under FEMA, the RBI’s Master Direction on Deposits and Accounts, and the Income-tax Act, 2025. Because repatriation limits, TDS rates and forms are exactly the kind of detail that regulators revise without fanfare, always confirm the current figure with your bank’s NRI desk or a chartered accountant before a large transaction.
Who These Accounts Are For
Under FEMA, a resident Indian who moves abroad is legally required to stop operating a standard resident savings account. There is no option to simply keep it running — RBI’s Master Direction is explicit that resident accounts must be redesignated once your status changes. NRE and NRO accounts exist to give you a compliant, FEMA-recognised way to hold rupees once that happens.
1
- Non-Resident Indians (NRIs) — Indian citizens living outside India.
- Persons of Indian Origin (PIOs) and Overseas Citizens of India (OCIs) — the PIO category has formally merged into OCI, but banks still use both terms.
- Citizens of Pakistan or Bangladesh require specific prior RBI approval before opening either account.
- Students studying abroad and merchant-navy seafarers are both explicitly confirmed by RBI as eligible for NRI account status, subject to the usual residency test.
2
- FEMA test (decides which bank account you must hold): you become a “person resident outside India” once you leave India for employment, business, or any purpose showing intent to stay abroad for an uncertain period — RBI treats this intention as the primary test, alongside a 182-day threshold in the preceding financial year.
- Income-tax residency test (decides what gets taxed): a separate day-count test — under 182 days, or a combined test across the current and preceding years — plus a Resident-but-Not-Ordinarily-Resident (RNOR) transition category for returning NRIs. It is entirely possible to be non-resident under FEMA in one part of the year and resident under the Income-tax Act for the same year.
- This mismatch is why an NRI who has just returned to India is often told to keep both an NRO and, for a period, an RFC (Resident Foreign Currency) account running side by side — the two laws are not tracking the same clock.
NRE Account: For Money You Earned Outside India
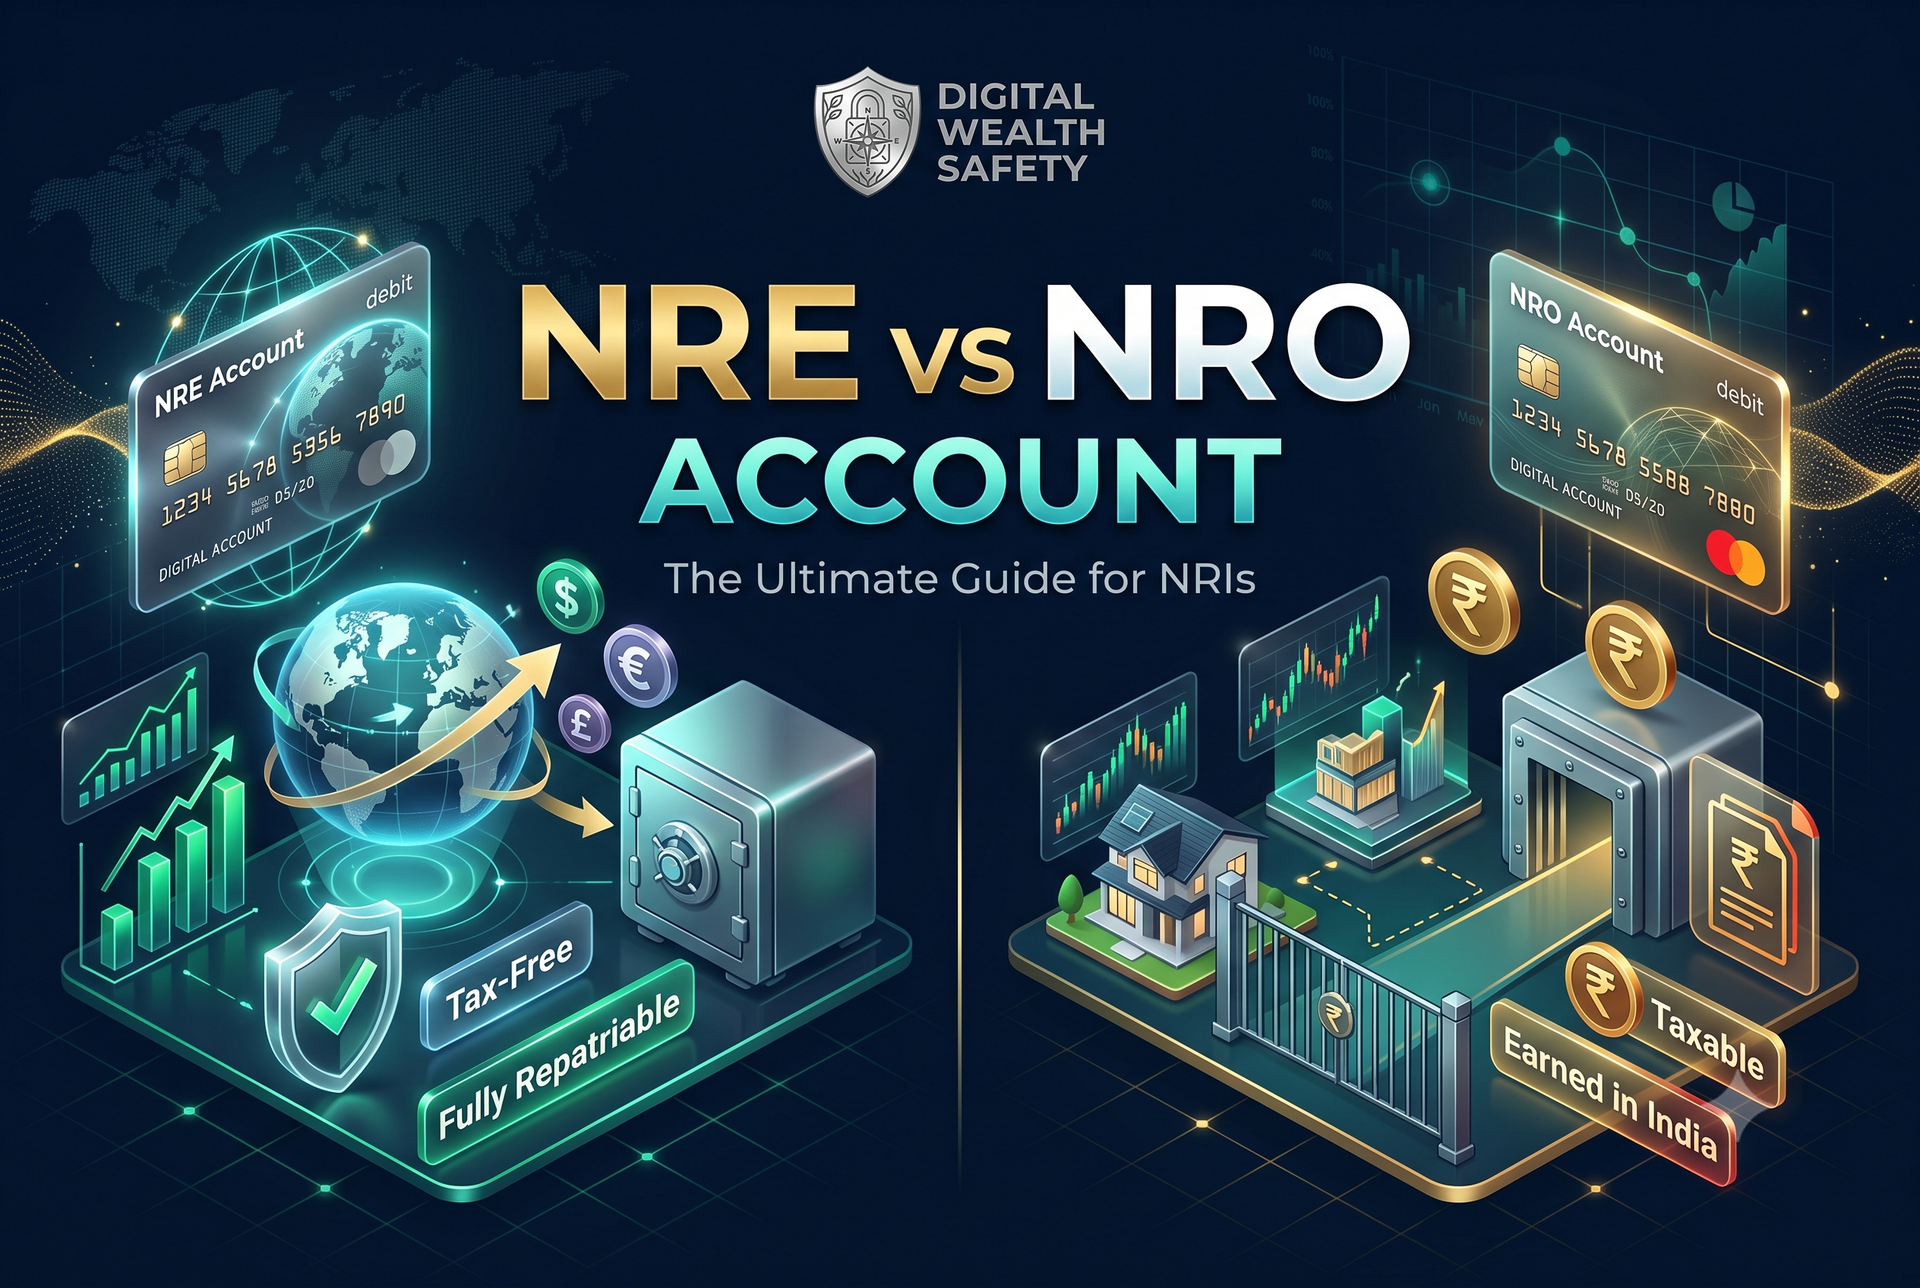
A Non-Resident External (NRE) Rupee account holds foreign earnings after they’ve been converted into rupees. It exists for one purpose: to let you park, invest, and freely move money you earned abroad, without India’s tax authorities taking a share of the interest.
A
- What can go in: inward remittances from abroad, transfers from another NRE/FCNR account, and — for certain routes — sale proceeds of property first credited to NRO and repatriated within limits. Indian-sourced income (rent, dividends, salary from an Indian employer, pension) cannot be credited to an NRE account.
- Taxability: interest is exempt from Indian income tax in full, for as long as you remain a non-resident under FEMA. The moment your residential status changes to resident, the exemption stops applying to interest earned from that point on — the account itself doesn’t change, but its tax treatment does.
- Repatriability: both principal and interest are freely and fully repatriable abroad, with no RBI approval and no annual ceiling.
- Account types: savings, current, recurring deposit, or fixed deposit — all rupee-denominated.
- Joint holding: with another NRI/OCI, or with a resident close relative (as defined under Section 2(77) of the Companies Act, 2013) on a “Former or Survivor” basis only — the resident joint holder cannot operate the account while the NRI is alive, except as a Power of Attorney or mandate holder.
- Investing from NRE: equity investments funded from an NRE account are treated as Foreign Direct Investment on a repatriation basis, with returns freely repatriable.
NRO Account: For Money You Earn Inside India
A Non-Resident Ordinary (NRO) Rupee account is the mandatory home for any income you continue to generate in India after becoming an NRI — rent from a flat, dividends on shares bought while you were a resident, a pension, or salary from an Indian employer. It is also what your existing resident savings account is redesignated into the day your status changes.
B
- What can go in: rental income, dividends, pension, business income, maturity proceeds of investments made while resident, and — commonly — the balance of a former resident savings account.
- Taxability: fully taxable in India. Banks deduct TDS at 30% plus applicable surcharge and cess at the time interest is credited — before you see a rupee of it. There is no NRI equivalent of Form 15G/15H to stop this deduction upfront; relief comes through a lower-TDS certificate or a tax return.
- Repatriability: capped at USD 1 million per financial year (April–March), net of applicable taxes, covering both current income and NRO balances together. The cap is tracked against your PAN, aggregated across banks.
- Account types: savings, current, recurring deposit, or fixed deposit.
- Joint holding: with a resident Indian on a “Former or Survivor” basis. Because NRO funds are not freely repatriable in the way NRE funds are, banks generally apply this rule more liberally than for NRE — some permit any resident joint holder, though many still ask for a close-relative relationship as a matter of internal policy, so confirm with your specific bank.
NRE vs NRO: Side by Side
| Feature | NRE Account | NRO Account |
|---|---|---|
| Full name | Non-Resident External Account | Non-Resident Ordinary Account |
| Source of funds | Income/savings earned outside India | Income earned or arising in India |
| Currency | Rupee-denominated (funded in forex, converted on deposit) | Rupee-denominated |
| Interest tax | Fully exempt while non-resident | Taxable; TDS at 30% + surcharge + cess |
| Repatriation | Fully and freely repatriable — no ceiling | Capped at USD 1 million/FY, net of tax |
| Can credit Indian income? | No | Yes — this is its purpose |
| 80TTA deduction | Not applicable (interest already exempt) | Up to ₹10,000 on savings interest, old regime only |
| Joint holding with resident | Close relative only, Former/Survivor | Resident, generally Former/Survivor |
| Remittance paperwork | None for standard transfers abroad | Form 145 (+ Form 146 above ₹5 lakh) required |
| On returning to India | Must be closed or converted to resident/RFC account | Simply redesignated as a resident account |
Tax Treatment in Detail
NRO Interest: The 30% TDS Rate, Explained
Interest credited to an NRO account is deducted at source at 30%, plus a surcharge that rises with your total income (broadly the same slab structure applied to resident taxpayers — nil below ₹50 lakh, rising through 10%, 15% and 25%, with the old tax regime permitting a higher top slab), plus a 4% health and education cess. At the base level this works out to roughly 31.2%; at the highest surcharge slab under the old regime it can approach the low-40s percent. If your actual tax liability is lower — which is common for NRIs whose only Indian income is this interest — the difference is claimed back by filing an income tax return.Section 80TTA Still Applies — With Conditions
NRIs can claim the Section 80TTA deduction of up to ₹10,000 on interest from an NRO savings account, on the same terms as residents. Three conditions commonly trip people up: it applies only to savings account interest, not fixed or recurring deposits; it is only available if you file under the old tax regime, since the new regime does not permit this deduction; and because NRE interest is already fully exempt, the deduction is only ever relevant to your NRO account.Using a DTAA to Cut the TDS Rate
India’s tax treaties with more than 75 countries typically cap the tax on bank interest at 10–15% under the treaty’s interest article, well below the 30% domestic default. To claim this at source rather than through a refund, you’ll need a Tax Residency Certificate (TRC) from your country of residence, a self-declaration in Form 10F, and confirmation that you have no permanent establishment in India — submitted to your bank before the interest is credited, or via a lower/nil-deduction certificate (Form 128, formerly Form 13) obtained from the tax department in advance.Repatriation: The USD 1 Million Rule and the New Forms
NRE money leaves India freely. NRO money does not — repatriation of NRO balances and current income together is capped at USD 1 million per financial year, per individual, under the Foreign Exchange Management (Remittance of Assets) Regulations, 2016. The same limit applies to voluntary transfers from your own NRO account into your own NRE account, which many NRIs use as a bridge to eventually move funds abroad.
→
- Pay the tax due on the underlying income before the transfer — the bank will not process the remittance otherwise.
- File Form 145 (the remitter’s declaration; this replaced Form 15CA from 1 April 2026) on the income-tax e-filing portal before the remittance.
- Obtain Form 146 — a Chartered Accountant’s certificate (this replaced Form 15CB) — for any taxable remittance exceeding ₹5 lakh, unless an Assessing Officer’s order already covers it.
- Submit an A2 form (the FEMA declaration) along with the bank’s own remittance request.
- Special cases — such as repatriating sale proceeds of certain immovable property beyond the standard limit — still require specific RBI approval.
Joint Holding and What Happens If the NRI Dies
On both account types, when a resident is added as a joint holder, the standard structure is “Former or Survivor”: the NRI (the “Former”) operates the account exclusively during their lifetime, and the resident (the “Survivor”) gains full operating rights only after the NRI’s death — at which point, if the survivor is the resident, the account is generally recategorised as a standard NRO/resident account going forward, since the exempt or freely-repatriable status was tied to the non-resident holder. Separately, RBI also permits the reverse arrangement — a resident’s own savings account can add an NRI close relative as a joint holder on an “either or survivor” basis, but that account remains a resident account throughout, subject to resident-account rules, and cannot receive the NRI’s own foreign remittances directly.
Costly Mistakes We See Repeatedly
This is a FEMA violation, not a technicality. The day your residential status changes, existing resident accounts must be redesignated to NRO (or NRE/RFC, as applicable) — continuing to operate them as resident accounts, even inadvertently, is exactly the kind of lapse RBI’s compounding proceedings exist for.
NRE accounts cannot legally hold Indian-sourced income. If this happens, banks are required to correct the categorisation, and the interest exemption on the misclassified funds does not survive the correction.
Many bank websites and RM scripts have not caught up to the 1 April 2026 switch to Form 145 and Form 146. Confirm the current form name and section reference directly before a large NRO remittance, rather than relying on older printed guidance.
The Golden Rule
If the money came from outside India, it belongs in NRE. If it was earned inside India, it belongs in NRO. Every other rule in this guide — taxability, repatriation limits, the forms you’ll need — follows directly from that one distinction.
Quick Reference: Where to Verify Current Rules
| For This Purpose | Authoritative Source / Portal |
|---|---|
| Deposit rules for NRE/NRO/FCNR accounts | RBI Master Direction — Deposits and Accounts (FED MD No. 14/2015-16, as updated) |
| Repatriation limits and asset remittance | Foreign Exchange Management (Remittance of Assets) Regulations, 2016 |
| Filing Form 145 / Form 146 for a remittance | Income-tax e-filing portal, under the Income-tax Act, 2025 and Income Tax Rules, 2026 |
| Claiming a reduced DTAA rate on NRO interest | Form 10F and Tax Residency Certificate, via your bank's NRI desk |
| Your own residential status under FEMA vs. tax law | RBI FAQs on Non-Resident Deposits; a chartered accountant for the Income-tax Act test |
NRE and NRO are not interchangeable variants of the same account — they are two different legal instruments answering two different questions: where did this money come from, and does India get to tax it. Get the source of funds right at the point of deposit, keep the 2026 form names straight when you remit from NRO, and re-verify the repatriation cap and TDS rate each year, since both are exactly the kind of figure that changes without most NRIs noticing.