Table of Contents
A Mumbai man died on 20 August 2013. He had written a Will. He had also named nominees on his mutual funds and fixed deposits. A little over eight months later, on 29 April 2014, a family member filed suit, and the question it was fighting over reached the Supreme Court of India only on 14 December 2023, more than ten years after his death
4
nominees now allowed on a bank depositof trading days closed at an all-time high
3
nominees on demat & MF folios (from Sept 2026)
15 days
calendar days for a bank to settle, once papers are complete
₹15 lakh
baseline limit for the simplified no-nominee route
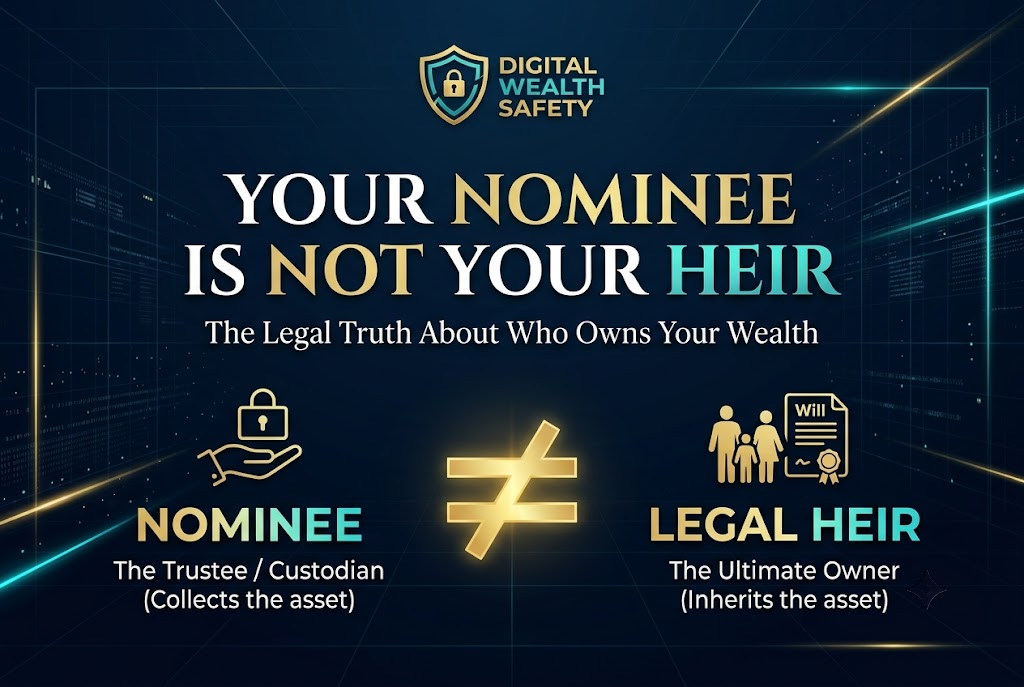
The question was simple: when a nominee and a legal heir both claim the same investment, who owns it? The Supreme Court’s answer was the legal heir. The nominee only holds the money until it reaches the people the law, or the Will, says it belongs to (Shakti Yezdani v. Jayanand Jayant Salgaonkar; case record).
Most Indian families believe the opposite. They fill in a nominee on every account form and assume the job is done. This guide explains why it is not, what changed in the law in 2025 and 2026, and the few steps that stop your family from spending a decade in court.
In brief
- A nominee is a caretaker, not an owner. The nominee receives the money; your Will, or succession law if there is no Will, decides who keeps it.
- Getting money out is now more predictable. Banks allow up to four nominees, demat accounts and mutual fund folios up to three, and banks must settle nominee claims within 15 calendar days of receiving all documents.
- Deciding who owns it is as hard as ever. The disputes have moved from the bank counter to the family.
- Life insurance is the one possible exception, and the High Courts disagree on it. Do not build a plan on it.
- The fix is alignment. Name nominees, write a valid Will, make the two say the same thing, and tell your family where everything is.
01 Nominee vs legal heir: two different questions
A nomination answers one question: whom should the bank, fund house or insurer pay? It does not answer the second question: who owns the money? That is settled by your Will, or, if you leave none, by the succession law that applies to your family.
Once the institution pays the nominee, its job is over. Indian courts have consistently held that the nominee then holds the money for the rightful owners. For shares and mutual funds, the Supreme Court said so directly in Shakti Yezdani (LiveLaw). For bank deposits, payment to a nominee discharges the bank, and the nominee holds the proceeds for the legal heirs (Moneylife on the RBI directions).
Question 1 · Access
Who gets paid?
Answered by: the nomination
The bank, fund house or insurer pays the nominee and is discharged. Fast, and now time-bound.
Question 2 · Ownership
Who keeps it?
Answered by: your Will, or succession law
The nominee holds the money in trust and must pass it to the rightful heirs.
The nomination only answers the first question. Life insurance is the one place where the courts are split, covered below.
The Supreme Court has applied this principle across several kinds of asset. Some statutory schemes have their own rules, so treat the table as a guide, not a rule for every benefit:
| Asset | Supreme Court case | What the Court held |
|---|---|---|
| Shares, mutual funds, demat holdings | Shakti Yezdani v. Jayanand Salgaonkar (2023) | Nomination under company and depository law is not a third mode of succession; the nominee holds for the heirs (source) |
| Housing society flat | Indrani Wahi v. Registrar of Co-operative Societies (2016) | The society must transfer membership to the nominee, but the other heirs remain free to claim their inheritance (source) |
| Bank deposit | Ram Chander Talwar v. Devender Kumar Talwar (2010) | Legal heirs, not the nominee, are entitled to the deposit (source) |
| Public Provident Fund | Shipra Sengupta v. Mridul Sengupta (2009) | The legal heir's claim prevails over the nominee's (source) |
| Life insurance (before 2015) | Sarbati Devi v. Usha Devi (1984) | The nominee is only an authorised hand to receive the money for the heirs (source) |
In the Mumbai case, the deceased had left a Will and nominations. The nominees claimed the mutual funds as theirs alone, while another family member asked the court to administer the whole estate. Paperwork existed on both sides; it simply did not agree, and that is what kept the family in court.
02 Who your legal heirs actually are
India has no single inheritance law. Which law applies depends mostly on your religion, and also on where you live: Uttarakhand now has its own Uniform Civil Code, and Goa has long had its own civil code. If you die without a Will, that law decides; if you leave one, it decides within the limits that law allows.
| Community | Law that applies | What it means for your heirs |
|---|---|---|
| Hindus, Buddhists, Jains, Sikhs | Hindu Succession Act, 1956 | If a Hindu man dies without a Will, his Class I heirs are his widow, sons, daughters and mother, plus the families of any children who died before him. The widow, each child and the mother take one equal share each (Section 10). |
| Muslims | Muslim personal law | A Will can generally pass on only one-third of the estate without the other heirs' consent; Sunni and Shia rules differ on bequests to heirs (Patra's Law Chambers). |
| Christians, Parsis and others | Indian Succession Act, 1925 | Succession follows the 1925 Act. |
| Residents of Uttarakhand (including those living outside the state), except Scheduled Tribes | Uniform Civil Code of Uttarakhand, in force since 27 January 2025 | Covers both Wills and intestate succession for those it applies to; Class I heirs include children, spouse and both parents (K S & K, Housing.com). Check whether it applies to you before relying on the rows above. |
A single nominee usually leaves out other first-line heirs. For example, a Hindu married man often names only his wife, yet his mother has an equal claim if he dies without a Will. The reverse happens too: in a 2025 Karnataka High Court case, a man had named only his mother on his insurance policies, and the court split the money equally between his mother, wife and child (see the insurance section below).
03 What changed in 2025 and 2026
Four rule changes since 2025 standardised how money is released after a death. None of them changed who owns it.
| Reform | In force | What it does |
|---|---|---|
| Mandatory probate removed (Section 213, Indian Succession Act omitted) | 20 Dec 2025 | Families covered by the old rule no longer need a court's probate before acting on a Will; probate is no longer a statutory prerequisite, though it can still be needed, especially when a Will is disputed (Bar & Bench) |
| Up to four bank nominees (Banking Laws Amendment Act, 2025) | 1 Nov 2025 | Deposits can have up to four nominees with set percentages, or in a priority order; lockers allow priority order only (Taxmann) |
| RBI claim-settlement directions for deceased customers | Issued 26 Sep 2025; banks to implement by 31 Mar 2026 | Standardises forms, documents and compensation. Nominees and survivors are paid without succession certificates; banks must settle within 15 calendar days of receiving all documents (a 15-day standard existed earlier too); no-nominee claims up to ₹15 lakh (₹5 lakh at co-operative banks), or a higher limit the bank sets, can use a simplified route (RBI directions, IndiaLaw) |
| Revised SEBI nomination norms for demat and mutual fund folios | Circular 29 May 2026; effective 1 Sep 2026 | Up to three nominees. New single-holder accounts must name a nominee or file an explicit opt-out; nomination is optional for joint holdings. Replaces all earlier SEBI nomination circulars, including the 2025 framework that had allowed up to ten (SEBI circular, TaxGuru summary) |
What this means for your family
With a nominee in place, the money now reaches someone within weeks. Without one, the simplified route covers balances up to ₹15 lakh (₹5 lakh at a co-operative bank, or a higher limit your bank sets), and only where there is no Will, no dispute and no court order. Above that, the bank will ask for a succession certificate, a legal heir certificate, or an affidavit from an independent person who knows the family, and may also ask for a surety (RBI directions). So nomination is more valuable than ever. It is just not the end of the job.
04 The exceptions people rely on, and why you shouldn't
Life insurance: an exception the courts can’t agree on
Since a 2015 amendment, Section 39(7) of the Insurance Act says that if you nominate your parents, spouse or children, they are “beneficially entitled” to the policy money. Read plainly, that makes them owners, not caretakers (AZB & Partners). The courts have not read it plainly:| For the nominee | For the heirs |
|---|---|
| High Courts including Andhra Pradesh and Bombay have held that such a family nominee owns the money, to the exclusion of other heirs (RawLaw summary). | The Karnataka High Court held in 2025 that the nominee keeps the money only if no legal heir claims it, and divided one man's policies equally between his mother, wife and child (Business Standard). |
| The Allahabad High Court took a similar view (Trilegal). |
Joint holdings: a joint name gives access, not automatic ownership
| Bank accounts held "Either or Survivor" | Demat accounts and mutual fund folios held jointly |
|---|---|
| The survivor can withdraw the money and the bank is discharged. But unless the facts show that the first holder meant the survivor to own it, the survivor must account to the first holder's legal heirs (Mondaq on Delhi High Court rulings). A joint name gives access, not automatic ownership. | On a joint holder's death, the holdings pass to the surviving holder through the institution's transmission process. SEBI's current nomination circular (29 May 2026) replaced the earlier rules that described this transfer as ownership, and does not restate that point (TaxGuru summary). Treat it as an operating step, not a decision on who owns the assets. If you want the survivor to keep everything, write that in your Will. |
05 Five family situations that turn into disputes
These are illustrations, not real cases, but each follows a pattern the courts see repeatedly.
1
Where does the day start?
Where do you wake up, and what is the first thing that begins the day? A day with no fixed beginning tends to have no fixed shape.
2
The nominee who wasn’t the intended heir
A woman writes a Will leaving her mutual funds to her two daughters, but her old folio still names her late husband’s brother. The fund house pays him. He holds the money in trust for the daughters, but they may have to fight to get it.
3
The joint account that “belonged” to the survivor
A father adds his son as joint holder on an “Either or Survivor” account to help with banking. After the father’s death, the son assumes it is now his. His sisters can claim their shares unless the son can show their father intended him to own it.
4
No nominee, no Will
A retired man’s ₹40 lakh fixed deposit has no nominee. Because the claim is above the ₹15 lakh simplified limit, the bank will ask for a succession certificate, a legal heir certificate, or an affidavit from an independent person known to the family. If the heirs disagree, only a court can settle it.
5
The nominee who died first
A man names his wife as sole nominee and she dies before him. He never updates the form. When he dies, there is no living nominee to pay, and the nomination does nothing for his wife’s own family. His children must go through the full succession process.
06 If a nominee or heir lives abroad
An heir living abroad faces the same law with more paperwork and less time on the ground. Preparing these in advance saves months:
| Prepare | Why it matters |
|---|---|
| PAN and an NRO account | Many institutions ask for a PAN, especially for securities and larger claims; check with each one. Inherited money from India is generally credited to an NRO account, not an NRE account (Belong). |
| An NRO demat account (for listed shares) | Inherited listed shares are usually received in a non-PIS NRO demat account; requirements depend on the asset and your depository participant (NRI Information). |
| Attested documents | Papers signed abroad are commonly apostilled (Hague Convention countries) or attested at an Indian embassy or consulate (Global Law Experts). Requirements vary by document and institution; for a death certificate issued abroad, RBI's bank directions also accept certification by an overseas branch of an Indian bank, a correspondent bank, a notary, magistrate or judge (RBI directions). |
| A power of attorney | To someone in India if you cannot attend court or the bank in person, attested the same way. |
| Repatriation limits | Inherited money can generally be remitted from the NRO account up to USD 1 million per financial year, subject to documentation (such as Forms 15CA/15CB) and applicable taxes; larger amounts need RBI approval (NRI Information). |
India has no inheritance tax, but the country you live in may require you to report the inheritance (NRI Information). For the account holder in India, the simplest help you can give an NRI heir is a nomination in their name and a Will that matches it.
07 The protection plan, step by step
STEP 1
Audit every nomination
List every account and check who is named on it. Most families find at least one that is missing, outdated or names someone who has died.
- Savings, current and fixed deposit accounts, and bank lockers
- Mutual fund folios and demat accounts
- Life and health insurance policies
- EPF, PPF, NPS and post office schemes
- Housing society membership
Use the new options. Split deposits and investments by percentage across several nominees instead of naming one person “for convenience”. For lockers, list nominees in priority order, because only successive nomination is allowed (Business Standard).
STEP 2
Write a valid Will
A Will does not need a lawyer, stamp paper or registration to be valid. What it needs:
- Your signature (or mark), made with a sound mind, at age 18 or older.
- Two witnesses. Each must either see you sign or receive your personal acknowledgement of your signature, and each must sign the Will in your presence. They do not have to be present at the same time (Captain Legal).
- Witnesses who inherit nothing. For Christians, Parsis and others under the Indian Succession Act, a gift to a witness or a witness’s spouse is void (Indian Kanoon, Section 67). The rule does not apply to Hindu Wills, but using independent witnesses is safest for everyone.
Strongly recommended, though not required for validity: name an executor you trust to carry the Will out. The law provides for administration where none is appointed, but an executor makes it far simpler. Registration is optional but worth it. An unregistered Will is fully valid, but it can be lost; registration keeps a safe copy (Moneylife). Probate is no longer a statutory prerequisite since 20 December 2025, though institutions may still ask for it on Will-based claims, and it gives a Will strong protection against later challenge (JSA).
Muslim readers should take advice on the one-third limit before drafting.
STEP 3
Make the nominations and the Will say the same thing
This is the step almost everyone skips, and the one that would have spared the Mumbai family a decade. For each asset, the nominee should be the person, or the people in the same percentages, that your Will leaves it to. Where that is not possible, name the nominee as an executor so the person receiving the money is also the person legally bound to pass it on.
Re-check both after any marriage, birth, divorce or death in the family.
★ The Golden Rule
Your nominee should be the same person your Will leaves the asset to. When the nomination and the Will agree, the money arrives fast and stays where you meant it. When they disagree, your family inherits a lawsuit.
STEP 4
Build an asset map, without passwords
Your family cannot claim what they cannot find. Write down what you own, where it is held, the account or folio number, and who the nominee is. Keep it with your Will and tell two people where it is.
Never put passwords, PINs or OTP access in this document. A list of accounts helps your heirs; a list of passwords helps a thief.
Unclaimed money is already a large problem. Deposits untouched for 10 years are moved to the RBI’s Depositor Education and Awareness Fund (Angel One), which now holds tens of thousands of crores of rupees in unclaimed money. If a relative has died, search the RBI’s UDGAM portal; it only locates deposits, and the claim is made with the bank itself (Upstox).
08 Safety warning: fraudsters watch for a death in the family
A bereaved family is an easy target. In one case SEBI investigated with the Delhi Police, callers posing as fund agents told a grieving father that his late son’s mutual funds were about to mature, and that he must invest more money first to receive the full amount (Business Standard, Capitalmind). The same script appears in many forms. Treat these as red flags:
| Red flag | How it typically sounds | The reality |
|---|---|---|
| Unsolicited contact about a dead relative's "unclaimed" or "maturing" money, with pressure to act through the caller | "Your father's funds are about to mature. We will help the family release them." | Banks do sometimes reach out about unclaimed deposits (Upstox), so contact alone proves nothing. Hang up and verify using the institution's official number or branch. |
| Inherited listed shares are usually received in a non-PIS NRO demat account; requirements depend on the asset and your depository participant (NRI Information). | "Pay the processing charge / top up the policy today, or the amount will lapse." | If you must pay more to receive money you are already owed, it is almost certainly a fraud. |
| Requests for OTPs, logins or the deceased's documents by phone or WhatsApp | "Share the OTP so we can verify you as legal heir." | Never share an OTP, password or PIN with any caller, whoever they claim to be. |
Safe action
Start every claim yourself, from the bank’s, fund house’s or insurer’s official website or branch. Banks must publish their claim forms and document lists on their websites; some also let you lodge claims online (RBI directions).
09 Frequently asked questions
10 Quick-reference helplines
| Where to go | For | Contact |
|---|---|---|
| RBI Ombudsman (CMS) | Bank delays a deceased-customer claim beyond 15 days or asks for extra documents | cms.rbi.org.in • Contact Centre 14448 |
| SEBI SCORES | Fund house, depository or broker dispute on transmission | scores.sebi.gov.in • 1800 266 7575 / 1800 22 7575 |
| IRDAI Bima Bharosa | Insurer delays or rejects a death claim | bimabharosa.irdai.gov.in • 155255 / 1800 4254 732 • complaints@irdai.gov.in |
| RBI UDGAM | Locate a deceased relative's unclaimed deposits | udgam.rbi.org.in |
| National Cyber Crime Helpline | Fraud call, fake agent or money lost to a scam | 1930 • cybercrime.gov.in |
Key Takeaway
A nomination gets the money out; your Will decides who keeps it. Name nominees on every account, write a valid Will, make the two say the same thing, and leave your family a map of where everything is. That one afternoon of paperwork is what stands between your family and a decade in court.
Sources
Law and regulations as of 17 October 2026. Watch for a Supreme Court ruling on Section 39(7) of the Insurance Act, which would change the insurance section.
Court rulings
- Shakti Yezdani v. Jayanand Salgaonkar, Supreme Court (LiveLaw) and case record with dates
- Indrani Wahi, housing society nomination (AZB & Partners)
- Joint holder or nominee: Supreme Court case survey (BCAJ)
- Karnataka High Court on insurance nominees (Business Standard)
- Insurance nominee rights and the High Court split (Trilegal)
- Bombay High Court on beneficial nominees (RawLaw)
- Survivor of joint bank account accountable to heirs (Mondaq)
Laws and regulations
- Banking Laws (Amendment) Act, 2025: four nominees (Taxmann)
- RBI deceased-customer claim directions (IndiaLaw), Probe42, Moneylife
- SEBI circular, 29 May 2026: modified nomination norms, TaxGuru summary
- RBI Directions on settlement of claims of deceased customers, 2025
- Uttarakhand Uniform Civil Code (K S & K), succession under the UCC (Housing.com)
- Omission of Section 213, Indian Succession Act (Bar & Bench), JSA
- Insurance Act Section 39(7) (AZB & Partners)
- Valid Will requirements, Section 63 (Captain Legal), Section 67 text (Indian Kanoon)
Data and NRI guidance